How to Budget a Biweekly Paycheck When You’re Living Paycheck to Paycheck
Getting paid every two weeks sounds simple until you actually try to live on it. One week you feel flush, and the next you’re counting coins for gas money, wondering how the math fell apart so fast. If you want to budget a biweekly paycheck without constantly feeling behind, the trick isn’t earning more money overnight — it’s learning how to map your income against your bills in a way that actually matches your pay schedule. That mismatch between when bills are due and when money lands in your account is often the real culprit behind that stuck, paycheck to paycheck feeling so many households know too well.
Why Biweekly Pay Makes Budgeting Feel Harder
Most bills are set up on a monthly cycle, but biweekly pay doesn’t divide evenly into months. You get 26 paychecks a year instead of 24, which means two months out of twelve bring a rare third paycheck. That’s genuinely good news, but if you’re not planning for it, the other ten months can feel tighter than they should because you unconsciously budget as if every month has that extra cushion. Add in rent due on the first, a car payment due on the fifteenth, and a paycheck that lands on random Fridays, and it’s easy to see why so many people feel like they’re guessing rather than planning. Recognizing this rhythm is the first real step toward taking control. If you want to dig deeper, our guide on Budgeting Methods Compared: Which One Actually Works? covers this in more detail. This is a common part of dealing with budget a biweekly paycheck, and it is worth keeping in mind.
Start by Mapping Your Pay Dates and Bills
Before you touch a budgeting app or spreadsheet, grab a calendar and write down your actual paycheck dates for the next three months, along with every bill’s due date. This single exercise reveals a lot. You’ll likely notice certain paychecks are stretched thinner because three or four bills cluster around the same payday, while other pay periods look relatively light. Once you see this pattern in black and white, you can start shifting due dates with creditors when possible, or simply plan ahead by setting aside money from the “lighter” paycheck to cover the “heavier” one. This visual mapping turns a vague sense of dread into a concrete, solvable puzzle. Many people run into this exact issue with budget a biweekly paycheck at some point.
How to Budget a Biweekly Paycheck Step by Step
Once you know your pay dates and bill dates, you can build a system that actually works with your schedule instead of against it. Try this basic approach: Keeping budget a biweekly paycheck in mind here will save you time later on.
- List your total take-home pay for each of the two paychecks separately, not as one combined monthly number.
- Assign specific bills to specific paychecks based on due dates, not guesswork.
- Set aside a small fixed amount from every check for savings, even if it’s just five or ten dollars to start.
- Leave a small buffer, maybe twenty or thirty dollars, unassigned in case a price is higher than expected.
- Review and adjust after each pay period rather than waiting a full month.
This paycheck-by-paycheck method feels more manageable than trying to picture an entire month at once, especially when money is tight. This connects closely with another common issue — see Zero-Based Budgeting Explained (With Free Template) for more on that. This detail matters more than it seems once budget a biweekly paycheck comes up again.
Splitting Bills Evenly Across Two Paychecks
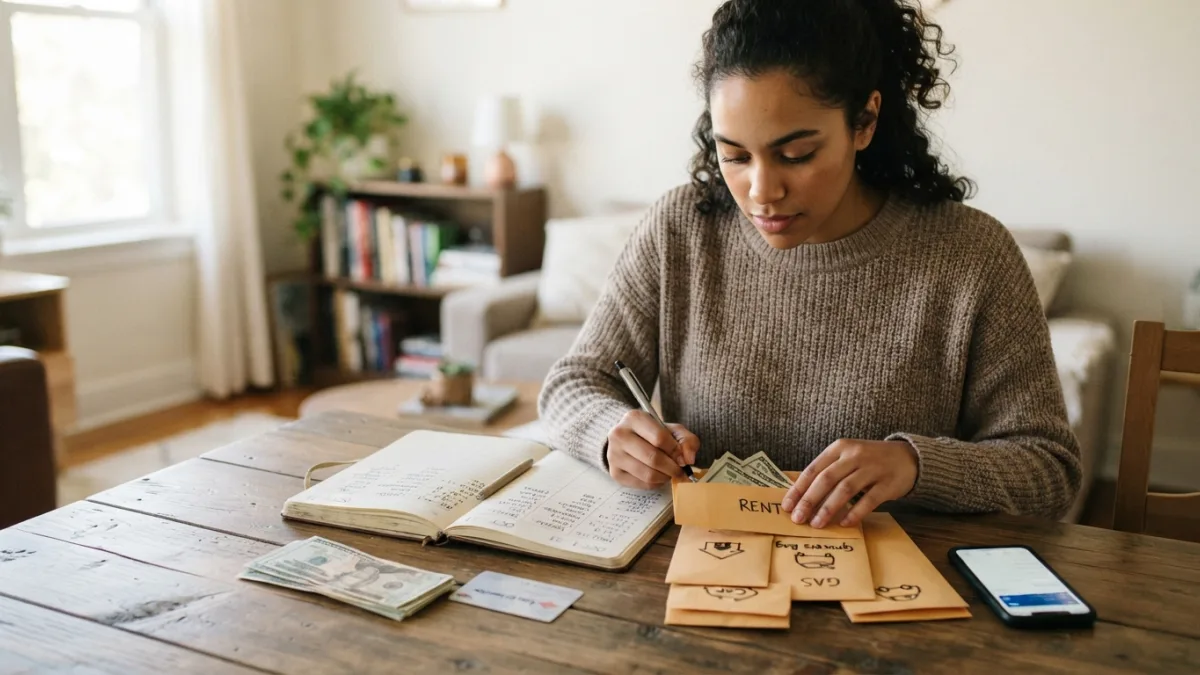
One of the most practical biweekly budgeting tips is dividing your monthly obligations in half and assigning a portion to each paycheck, rather than paying everything in one lump sum from a single check. If your rent is $1,200, for example, set aside $600 from each paycheck instead of trying to pull the full amount from one. This softens the blow considerably and prevents that scary feeling of watching an entire paycheck disappear the moment it arrives. It also builds a habit of treating savings and bill payments as non-negotiable line items rather than whatever’s left over. Automating these transfers, even small ones, removes the temptation to spend the money before the bill comes due. It is one of those small things that makes budget a biweekly paycheck easier to manage overall.
Building an Emergency Fund on a Tight Budget
It sounds almost impossible when every dollar already has a job, but building even a small emergency fund on a tight budget changes everything about how secure you feel. Start absurdly small if you have to — five dollars per paycheck adds up to $130 a year, which might not sound like much, but it’s often enough to cover a flat tire or a surprise co-pay without reaching for a credit card. The goal isn’t to hit some magic number overnight; it’s to build the habit of paying yourself first, even in tiny amounts. Many banks let you automate this transfer the same day your paycheck lands, so the money moves before you have a chance to spend it elsewhere. This is a common part of dealing with budget a biweekly paycheck, and it is worth keeping in mind.
Handling the Three-Paycheck Months
Twice a year, depending on your pay schedule, you’ll get three paychecks in a single month instead of two. This is where a lot of financial breathing room can happen if you plan for it. Instead of treating that extra check as bonus spending money, consider directing most of it toward your emergency fund, a debt payment, or a bill you’ve been struggling to keep current. Mark these bonus months on your calendar in advance so you’re not caught off guard, and decide ahead of time exactly where that money will go. Deciding in the moment often leads to it disappearing on things you won’t even remember buying a week later. You might also find our article on The 50/30/20 Budget Rule: Does It Actually Work? helpful here. Many people run into this exact issue with budget a biweekly paycheck at some point.
Biweekly Budgeting Tips When Income Is Irregular
Budgeting for irregular income adds another layer of difficulty on top of a biweekly schedule, especially for freelancers, gig workers, or anyone whose hours fluctuate. In this case, it helps to budget based on your lowest expected paycheck rather than your average one. Whatever comes in above that baseline becomes a bonus that goes straight to savings, debt, or upcoming irregular expenses like car repairs. Keeping a running list of your last six months of paycheck amounts can help you spot a realistic low-end number to plan around. This approach protects you from the trap of budgeting optimistically and then scrambling when a slower pay period arrives unexpectedly. Keeping budget a biweekly paycheck in mind here will save you time later on.
Tools That Make This Easier
You don’t need expensive software to manage a paycheck to paycheck budget effectively. A simple notebook, a spreadsheet, or a free budgeting app can all work as long as you actually use it consistently. Look for tools that let you plan by pay period rather than by calendar month, since that will match your real cash flow much more closely. Many banking apps now offer features that let you label specific savings goals, like “rent” or “emergency fund,” within your account, which makes it easier to avoid accidentally spending money that’s already been mentally assigned elsewhere. Whatever system you choose, the best one is simply the one you’ll stick with on a regular basis. This detail matters more than it seems once budget a biweekly paycheck comes up again.
What to Do When an Unexpected Expense Hits
Even the best plan gets tested by a surprise vet bill or a sudden home repair. When that happens, resist the urge to abandon your budget entirely out of frustration. Instead, look at your upcoming paychecks and figure out which non-essential spending category can absorb the hit temporarily, whether that’s dining out, subscriptions, or discretionary shopping. If you’ve built even a small emergency fund, this is exactly the moment to use it, then focus the next few paychecks on rebuilding that cushion. Treating setbacks as temporary adjustments rather than total failures keeps you motivated to stay with the system instead of giving up on budgeting altogether. For a related walkthrough, check out How to Build Your First Budget (Beginner's Guide). It is one of those small things that makes budget a biweekly paycheck easier to manage overall.
Living paycheck to paycheck can feel like running on a treadmill that never slows down, but a biweekly budget built around your actual pay dates gives you back a sense of control. It won’t fix everything overnight, and there will still be tight weeks, but small consistent habits — splitting bills, saving a little from every check, and planning ahead for three-paycheck months — add up faster than most people expect. The goal isn’t perfection; it’s progress that compounds over time until that constant financial anxiety starts to ease. This is a common part of dealing with budget a biweekly paycheck, and it is worth keeping in mind.
Frequently Asked Questions
How do I budget a biweekly paycheck if my bills don’t line up with my pay dates?
Map out your bill due dates against your paycheck dates for a few months, then split larger bills into two smaller amounts pulled from each paycheck. This spreads the cost evenly instead of draining one check completely. Many people run into this exact issue with budget a biweekly paycheck at some point.
How much should I save from each paycheck if money is tight?
Start with whatever feels manageable, even five or ten dollars per paycheck. Consistency matters more than the amount at first, and you can increase it gradually as your situation improves. Keeping budget a biweekly paycheck in mind here will save you time later on.
What should I do with the extra paycheck in a three-paycheck month?
Plan ahead and direct most of it toward savings, debt, or a bill you’ve fallen behind on, rather than treating it as extra spending money. This detail matters more than it seems once budget a biweekly paycheck comes up again.
Is it possible to build an emergency fund while living paycheck to paycheck?
Yes, though it takes patience. Automating small transfers on payday, even tiny ones, builds the habit and slowly creates a cushion for unexpected expenses. It is one of those small things that makes budget a biweekly paycheck easier to manage overall.
How do I handle budgeting with irregular income on top of biweekly pay?
Base your budget on your lowest typical paycheck amount rather than an average. Any extra income beyond that baseline can go toward savings or upcoming irregular costs. This is a common part of dealing with budget a biweekly paycheck, and it is worth keeping in mind.